


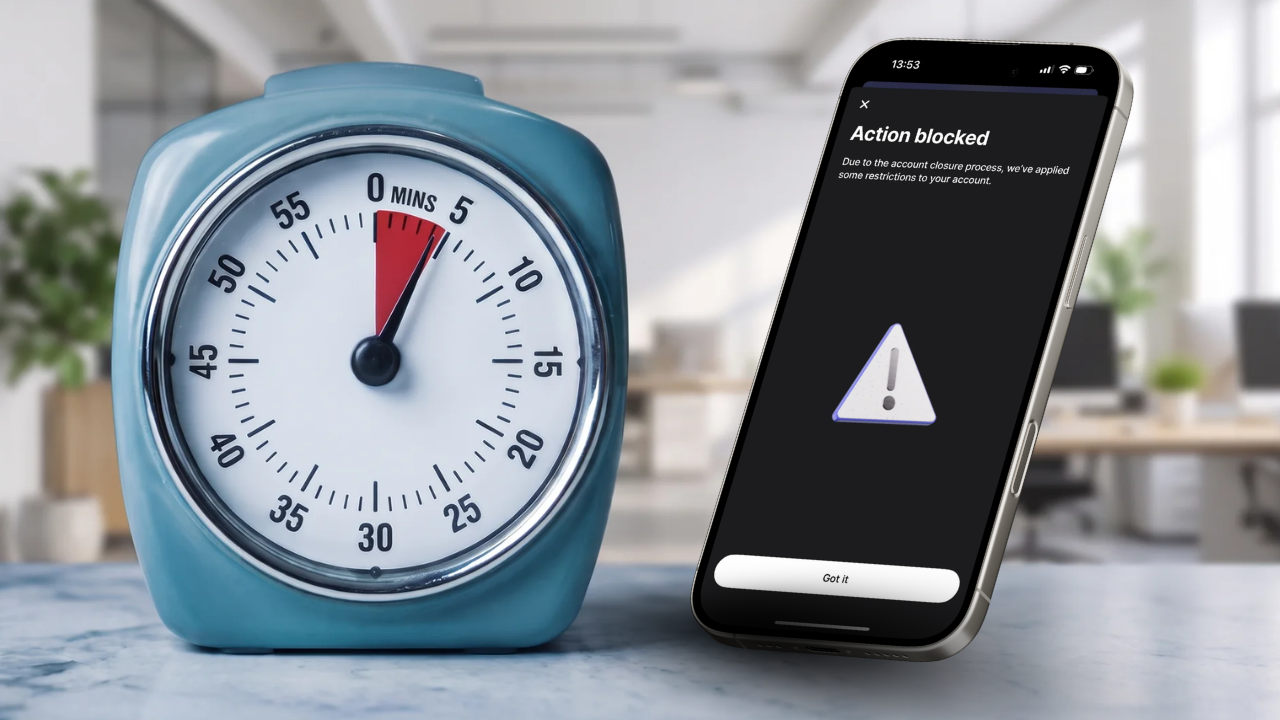
Most fintech platforms advertise the same thing as a selling point: “open an account in a few minutes”. Some boast opening in seconds. The assumption is that this is a quality signal: an efficient bank is a reliable bank, speed equals sophistication.
The data from 2026 suggests the exact opposite.
A fintech that opens an account in five minutes has invested five minutes in deciding whether to accept you as a client.
It has verified that you’re not on a sanctions list and that your documents aren’t obviously fake. End.
Everything else (the provenance of funds, the structure of your business, the transaction pattern you typically have) is not evaluated at opening. It is evaluated afterwards, at the moment when you’ve already deposited your capital and are trying to move it.
What “account opened in 5 minutes” really means
Due diligence doesn’t disappear when onboarding is fast. It shifts.
The business model of fintech platforms with ultra-rapid onboarding is structured in a precise way: accept everyone, then filter problems afterwards.
The point is that when the platform filters, it’s you who experience the operational friction.
Your transfer stays blocked while they ask for documents.
Your account gets limited while they execute their compliance review.
Your problem, their timelines.
Document requests can arrive in stages, from different departments, for the same transaction.
Those who have operated with amounts of hundreds of thousands and millions of euros on these platforms know this: the cost of a “fast” relationship at opening is paid at the worst moment, when that transfer needs to leave immediately.
How opening at a high-level physical bank works
High-level international physical banks, for example, have onboarding processes that typically require months for a standard profile.
And the process typically includes certified identity documentation, proof of residence, 2-3 years of fiscal documentation, a complete review of the origin of funds, a banking reference, and a compliance officer who reads the file before any opening decision.
This is not slow administration: it’s the real work of understanding who a client is before accepting their capital.
When opening is approved at an institution with adequate due diligence, the relationship manager assigned to the account has read your file.
They know what your business does and where the revenue comes from, and they have a reference for what a normal month of transactions looks like for you.
This understanding has a direct consequence on the daily experience: the bank doesn’t need to interrogate you about every payment because it already has a reference for your activity.
An important transfer toward a partner in Singapore doesn’t trigger a block because the institution knows it’s consistent with how you operate.
The harder it is to get in, the more protected you are once inside.
This is exactly how risk management works when done correctly, even if it initially seems paradoxical.
Revolut and the sanction of over 11 million euros
A glaring and recent example.
On April 2, 2026 the Italian Competition and Market Authority imposed on Revolut a total sanction exceeding 11 million euros, articulated in three distinct violations.
- Five million for misleading advertising on investment products.
- Five million, and this is the official wording of the provision, for the “aggressive management of account blocking and suspension conditions, with inadequate notice and inadequate customer assistance”.
- And 1.5 million for not having provided clear information about which IBAN customers were actually receiving.
The authority, after a formal investigation, concluded in writing that one of the most used fintech platforms in Europe was systematically managing account restrictions in ways legally classified as aggressive, without adequate notice and without the customer support to resolve them.
If you have significant capital passing through a digital platform and want to understand whether your infrastructure will hold when you really need to move that money, the first step is a preliminary analysis of the case with the GloboBanks team: it serves to make an honest mapping of your operational exposure before the problem manifests. Contact the office here.
What changes after a well-done due diligence
The other side of the coin (what the daily banking experience becomes when the institution has done the upfront work) is the part that most clients only discover after having already lived the alternative.
When a serious bank has built a complete picture of who you are before accepting your capital, the daily operational relationship works in a structurally different way.
The relationship manager assigned to your account is a real person in flesh and blood with a name and phone number. If something unusual emerges, they call you and ask.
In short, it’s effectively a banking relationship that prioritizes assistance and the wellbeing of the client.
The compliance review that seemed invasive at opening is exactly what makes the relationship frictionless afterwards. The bank already knows who you are and doesn’t need to keep asking.
Want to understand whether your current banking infrastructure will hold when you really need it?
The first step is a preliminary analysis of the case with a senior consultant of the GloboBanks team.
In that conversation we map where you hold your capital today, what type of transactions you typically make, and whether the setup you have truly holds your operability without interference when it counts.
If the account you were counting on for a transfer of hundreds of thousands of euros was opened in two minutes by a platform that focuses on marketing and finding as many clients as possible, this is the conversation to have before needing that account to work.
Write at this link to book your preliminary analysis.
